IRA Owner and Beneficiary Errors Under the New IRS Correction Program: When to File and How
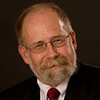
Bob Toth has practiced employee benefits law since 1983, in a practice that combines ERISA, tax law, insurance law, securities law, and investment law for 401(a), 403(b), and 457 plans. He has served as EP Program Chair of the IRS Great Lakes TE/GE Council and has held leadership positions with the National IRS TE/GE Council. He is Principal of the Law Offices of Robert J. Toth, Jr., LLC, in Fort Wayne, Indiana, and for more than a decade has served as Of Counsel to the attorneys and clients of the Fiduciary Law Center (previously the Retirement Law Group).
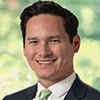
Peter E. Moshang is Co-Chair of the IRA Plans & Distributions Committee for the American Bar Association Real Property Trusts & Estate Section, and he has spoken and written on estate planning with retirement assets since 2016. In February 2026 he co-presented “Challenges Associated with Self-Directed Individual Retirement Accounts and Investments in ‘Unique’ or Alternative Assets” for the Section's Employee Plans and Executive Compensation Group.
Live Video-Broadcast: December 17, 2026
2 hour CLE
Tuition: $195.00
Co-Sponsored by myLawCLE
Get this course, plus over 1,000+ of live webinars.
Learn More
Training 5 or more people?
Sign-up for a law firm subscription plan and each attorney in the firm receives free access to all CLE Programs
Program Summary
Before You Pay the $3,500 Fee, Decide Whether It Is the Right Fix
Beginning May 1, 2027, Revenue Procedure 2026-33 opens the IRS Voluntary Correction Program for IRAs. It carries a $3,500 fee and creates a new path for custodian-caused errors. That path sits alongside existing relief for missed 60-day rollovers under Rev. Proc. 2020-46 and Rev. Proc. 2003-16.
Treat the client's own mistake as a provider error, and the file belongs on the Form 5329 route instead. Overlook the wrong-account cutoff or the refund period, and a deadline closes before you file. Pay for an IRS ruling when an automatic waiver or free self-certification is available, and the client funds relief already in hand. Win approval, and a 90-day correction window starts to run.
You leave with decision trees, a deadline calendar, demand-letter language, a waiver evidence index, and a small-account cost test. These are judgment tools for a live file with incomplete facts. Use them to choose the route before paying any fee: custodian-filed correction, automatic waiver, self-certification, a paid IRS ruling, an amended return, or no filing.
Key topics to be discussed:
- Intake and Eligibility Gates
Test each file against the Rev. Proc. 2026-33 intake gates and the three provider-error failure definitions, and confirm whether a 60-day rollover failure is eligible for the IVCP, before paying the $3,500 fee. - Provider Error or Client Mistake
Separate a custodian's error from the client's own mistake, and move the client's-own-mistake file onto the Form 5329 route. - Applicant, Payer, and Package
Establish who applies and who pays, press the custodian to file, and build the submission package around demand-letter and cover-letter language. - Deadlines and Small-Account Costs
Sequence deadline triage, protective refund claims, and the post-approval 90-day window with the receiving custodian, and weigh cost against benefit on small accounts. - Existing Rollover Waiver Routes
Apply the automatic waivers, self-certification, and IRS relief filings under Rev. Proc. 2020-46 and Rev. Proc. 2003-16, and track the changes required as those waiver procedures are incorporated into the IVCP. - Submission Route Through 2027
Compare an IVCP submission with a PLR submission, use the existing submission processes until Rev. Proc. 2027-4 is issued, and work within the corrections limitations and requirements.
This course is co-sponsored with myLawCLE.
Date / Time: December 17, 2026
- 12:00 pm – 2:10 pm Eastern
- 11:00 am – 1:10 pm Central
- 10:00 am – 12:10 pm Mountain
- 9:00 am – 11:10 am Pacific
 Closed-captioning available
Speakers
Bob Toth, Principal | Law Offices of Robert J. Toth, Jr., LLC; Of Counsel | Fiduciary Law Center
Bob Toth has practiced employee benefits law since 1983, in a practice that combines ERISA, tax law, insurance law, securities law, and investment law for 401(a), 403(b), and 457 plans. He has served as EP Program Chair of the IRS Great Lakes TE/GE Council and has held leadership positions with the National IRS TE/GE Council. He is Principal of the Law Offices of Robert J. Toth, Jr., LLC, in Fort Wayne, Indiana, and for more than a decade has served as Of Counsel to the attorneys and clients of the Fiduciary Law Center (previously the Retirement Law Group).
- Education & Credentials
He graduated from the University of Michigan in 1978 and from Wayne State University Law School in 1983. He is licensed to practice in Indiana and Michigan and is admitted to the U.S. District Court for the Eastern District of Michigan.
- Recognition & Leadership
He has been a Fellow of the American College of Employee Benefits Counsel since 2007. Beyond his work with the IRS TE/GE Councils, he chairs the Subcommittee on DC Lifetime Income of the American Bar Association Taxation Section’s Employee Benefits Committee. With the American Retirement Association/American Society of Pension Professionals and Actuaries, he served as Senior Adviser to the ASPPA Government Affairs Committee, Chair of the NTSA government affairs subcommittee, and Chair of the 403(b) Transparency Task Force. He is a Past Chair of the American Council of Life Insurance’s Pension Committee, a past member of the Advisory Board of the American Benefits Council, and a co-founder, former Chair, and Board Member of ABC of Northern Indiana, and he served on the Great Lakes Benefits Conference Executive Committee.
- Professional Involvement
He is an Adjunct Professor in the Employee Benefits LLM Program at John Marshall School of Law, where he teaches the 403(b) and 457 plan courses, and he sits on the John Marshall Law School Employee Benefits Advisory Board and the Tax Facts Advisory Board. He is an active member of the Employee Benefits Committee of the American Bar Association’s Taxation Section and a co-founder of the Institute for Pension Plan Management at Purdue University. His professional associations also include the Indiana State Bar Association, the Michigan State Bar Association, and the Allen County Bar Association. He speaks frequently on topical retirement plan issues, is widely published in academic and professional publications, and maintains a blog at businessofbenefits.com.
- Experience
His practice focuses on the design, administration, and distribution of financial products and services for retirement plans. That work has included advising on prohibited transaction issues related to retirement plan products and services and their distribution, writing and implementing standards for fiduciary and advisory practices, implementing and maintaining 403(b) programs, and designing investment products for 401(k) plans. It has also included the design of lifetime income programs for defined contribution plans, multiple employer plans and pooled employer plans, the integration of internationally based U.S. retirement plans, and annuity products for employer-based retirement plans.
Before opening Toth Law in 2009, he was a partner at Baker and Daniels (now Faegre Drinker Biddle). He spent 17 years in the legal division of Lincoln National Corporation, where he was Associate General Counsel managing the legal affairs of Lincoln Financial Group’s employer market division. Earlier, he was a Senior Attorney at Kellogg Company in Battle Creek, Michigan, serving as in-house counsel on the company’s benefit law issues.
Peter E. Moshang, Partner | Heckscher, Teillon, Terrill & Sager, PC
Peter E. Moshang is Co-Chair of the IRA Plans & Distributions Committee for the American Bar Association Real Property Trusts & Estate Section, and he has spoken and written on estate planning with retirement assets since 2016. In February 2026 he co-presented “Challenges Associated with Self-Directed Individual Retirement Accounts and Investments in ‘Unique’ or Alternative Assets” for the Section’s Employee Plans and Executive Compensation Group. He is a partner at Heckscher, Teillon, Terrill & Sager, PC, where his practice centers on estate planning, trust and estate administration, and estate and gift taxation.
- Education & Credentials
He earned his J.D., cum laude, from Boston University School of Law in 2013, where he was Editor-in-Chief of the American Journal of Law & Medicine. He holds a B.A. in Political Science (with departmental honors) and Economics, summa cum laude and Phi Beta Kappa, from the University of Richmond (2010). He was admitted to practice in Pennsylvania and New Jersey in 2013 and in Florida in 2018.
- Recognition & Leadership
He was elected a Fellow of the American College of Trust and Estate Counsel (ACTEC) in 2025. That year he also graduated from the fourth session of the Mid-Atlantic Fellows Institute, an ACTEC-sponsored six-session education program designed to develop future leaders of trust and estate practice, for which he was nominated. Thomson Reuters named him a Rising Star Super Lawyer in trust and estate law from 2019 to 2022, and he was named to Best Lawyers: Ones to Watch in America (2023).
- Professional Involvement
He has co-chaired the American Bar Association’s IRA Plans & Distributions Committee since 2025, after serving as its Vice-Chair from 2024 to 2025. From 2023 to 2025 he sat on the Executive Committee of the Philadelphia Bar’s Probate and Trust Law Section. He is a member of the Philadelphia, Pennsylvania, New Jersey, Florida, and Montgomery County bar associations, the Montgomery County Estate Planning Council, and the Philadelphia Estate Planning Council.
- Experience
His retirement-asset programs include “Five Years of SECURE” (Pennsylvania Bar Institute, 32nd Annual Estate Law Institute, November 2025), “Planning with Qualified Retirement Benefits” (American Bar Association Real Property Trust and Estate Law Section, Employee Plans and Executive Compensation Group, March 2025), “Impact of the SECURE Act and Final Regulations” (Pennsylvania Bar Institute Estate and Elder Law Symposium, February 2025), and “Administering An Estate With Retirement Assets” (Pennsylvania Bar Institute, 26th Estate Law Institute, November 2019).
He is the author of “IRS Issues Final Regulations for SECURE Act 1.0 (and Proposed Regulations for SECURE Act 2.0)” (December 2024) and “SECURE Act 2.0 Includes Additional Changes for Estate Planning Clients” (May 2023), both in the Philadelphia Bar Association Probate and Trust Law Section Newsletter, and of “Step It Up! Achieving Basis Adjustments for Certain Trust Assets Using Formula General Powers of Appointment” (Estate Planning Journal, December 2024).
His practice areas are estate and tax planning, estate and trust planning, and estate and gift taxation. During law school he served as a summer law clerk to President Judge Susan Peikes Gantman in the Pennsylvania Superior Court.
Agenda
SESSION 1 – Fixing Custodian-Caused Inherited IRA and Wrong-Account Errors in the New IRS Program | Peter E. Moshang | 12:00pm – 1:00pm
This session works through the owner-side intake under the new IRA Voluntary Correction Program in Rev. Proc. 2026-33, from the seat of counsel representing IRA owners and inherited-IRA beneficiaries. It opens with the intake gates to clear before the $3,500 fee is paid, then turns to the question that decides the route: provider error or the client’s own mistake. For a provider error, the hour covers fitting the facts to the three provider-error failure definitions, who applies and who pays, and getting the custodian to file and pay. For the client’s-own-mistake file, it covers the Form 5329 route.
The session then moves to timing and execution. It covers deadline triage and protective refund claims, including how to sequence the wrong-account cutoff, the refund period and the 90-day correction window. It closes with building the submission package, what follows after approval with the 90-day window and the receiving custodian, and weighing cost against benefit on small accounts.
BREAK | 1:00pm – 1:10pm
SESSION 2 – Rescuing a Missed 60-Day Rollover From Free Self-Certification to the Paid IRS Waiver | Bob Toth | 1:10pm – 2:10pm
This one-hour individual-tax session for owner-side counsel addresses rescuing a missed 60-day rollover in 2027. It opens with the existing rules for handling a missed 60-day deadline prior to Rev. Proc. 2026-33, under Rev. Proc. 2020-46 and Rev. Proc. 2003-16, including the § 3.03 automatic waiver, self-certification and filing for relief with the IRS. It then examines the eligibility of a 60-day rollover failure to be treated under the new ICRS and the IVCP, how the existing waiver procedures are incorporated into the IVCP, and the changes required.
The session then turns to the filing decision. It covers the use of existing submission processes until Rev. Proc. 2027-4 is issued, a comparison of IVCP submissions to PLR submissions, and which process to use through 2027. It closes with corrections limitations and requirements and the waiver narrative itself.
Credits
Alaska
Approved for CLE Credits
2 General
Alabama
Pending CLE Approval
2 General
Arkansas
Approved for CLE Credits
2 General
Arizona
Approved for CLE Credits
2 General
California
Approved for CLE Credits
2 General
Colorado
Pending CLE Approval
2 General
Connecticut
Approved for CLE Credits
2 General
District of Columbia
No MCLE Required
2 CLE Hour(s)
Delaware
Pending CLE Approval
2 General
Florida
Approved via Attorney Submission
2 General Hours
Georgia
Pending CLE Approval
2 General
Hawaii
Approved for CLE Credits
2 General
Iowa
Pending CLE Approval
2 General
Idaho
Pending CLE Approval
2 General
Illinois
Pending CLE Approval
2 General
Indiana
Pending CLE Approval
2 General
Kansas
Pending CLE Approval
2 Substantive
Kentucky
Pending CLE Approval
2 General
Louisiana
Pending CLE Approval
2 General
Massachusetts
No MCLE Required
2 CLE Hour(s)
Maryland
No MCLE Required
2 CLE Hour(s)
Maine
Pending CLE Approval
2 General
Michigan
No MCLE Required
2 CLE Hour(s)
Minnesota
Pending CLE Approval
2 General
Missouri
Approved for CLE Credits
2.4 General
Mississippi
Pending CLE Approval
2 General
Montana
Pending CLE Approval
2 General
North Carolina
Pending CLE Approval
2 General
North Dakota
Approved for CLE Credits
2 General
Nebraska
Pending CLE Approval
2 General
New Hampshire
Approved for CLE Credits
120 General minutes
New Jersey
Approved for CLE Credits
2 General
New Mexico
Approved for CLE Credits
2 General
Nevada
Pending CLE Approval
2 General
New York
Approved for CLE Credits
2 General
Ohio
Pending CLE Approval
2 General
Oklahoma
Pending CLE Approval
2.5 General
Oregon
Pending CLE Approval
2 General
Pennsylvania
Approved for CLE Credits
2 General
Rhode Island
Pending CLE Approval
2.5 General
South Carolina
Pending CLE Approval
2 General
South Dakota
No MCLE Required
2 CLE Hour(s)
Tennessee
Pending CLE Approval
2 General
Texas
Approved for CLE Credits
2 General
Utah
Pending CLE Approval
2 General
Virginia
Not Eligible
2 General Hours
Vermont
Approved for CLE Credits
2 General
Washington
Approved via Attorney Submission
2 Law & Legal Hours
Wisconsin
Pending CLE Approval
2 General
West Virginia
Pending CLE Approval
2.4 General
Wyoming
Pending CLE Approval
2 General
More CLE Webinars
Trending CLE Webinars
Upcoming CLE Webinars
© 2026 Federal Bar Association